Apple Pay finally arrives in India — but only Axis Bank cardholders get in on day one
Apple has launched Apple Pay in India, nine years after its US debut, initially supporting only Axis Bank-issued Visa and Mastercard credit cards. Users can tap to pay on iPhone, iPad and Apple Watch; UPI support is missing at launch.
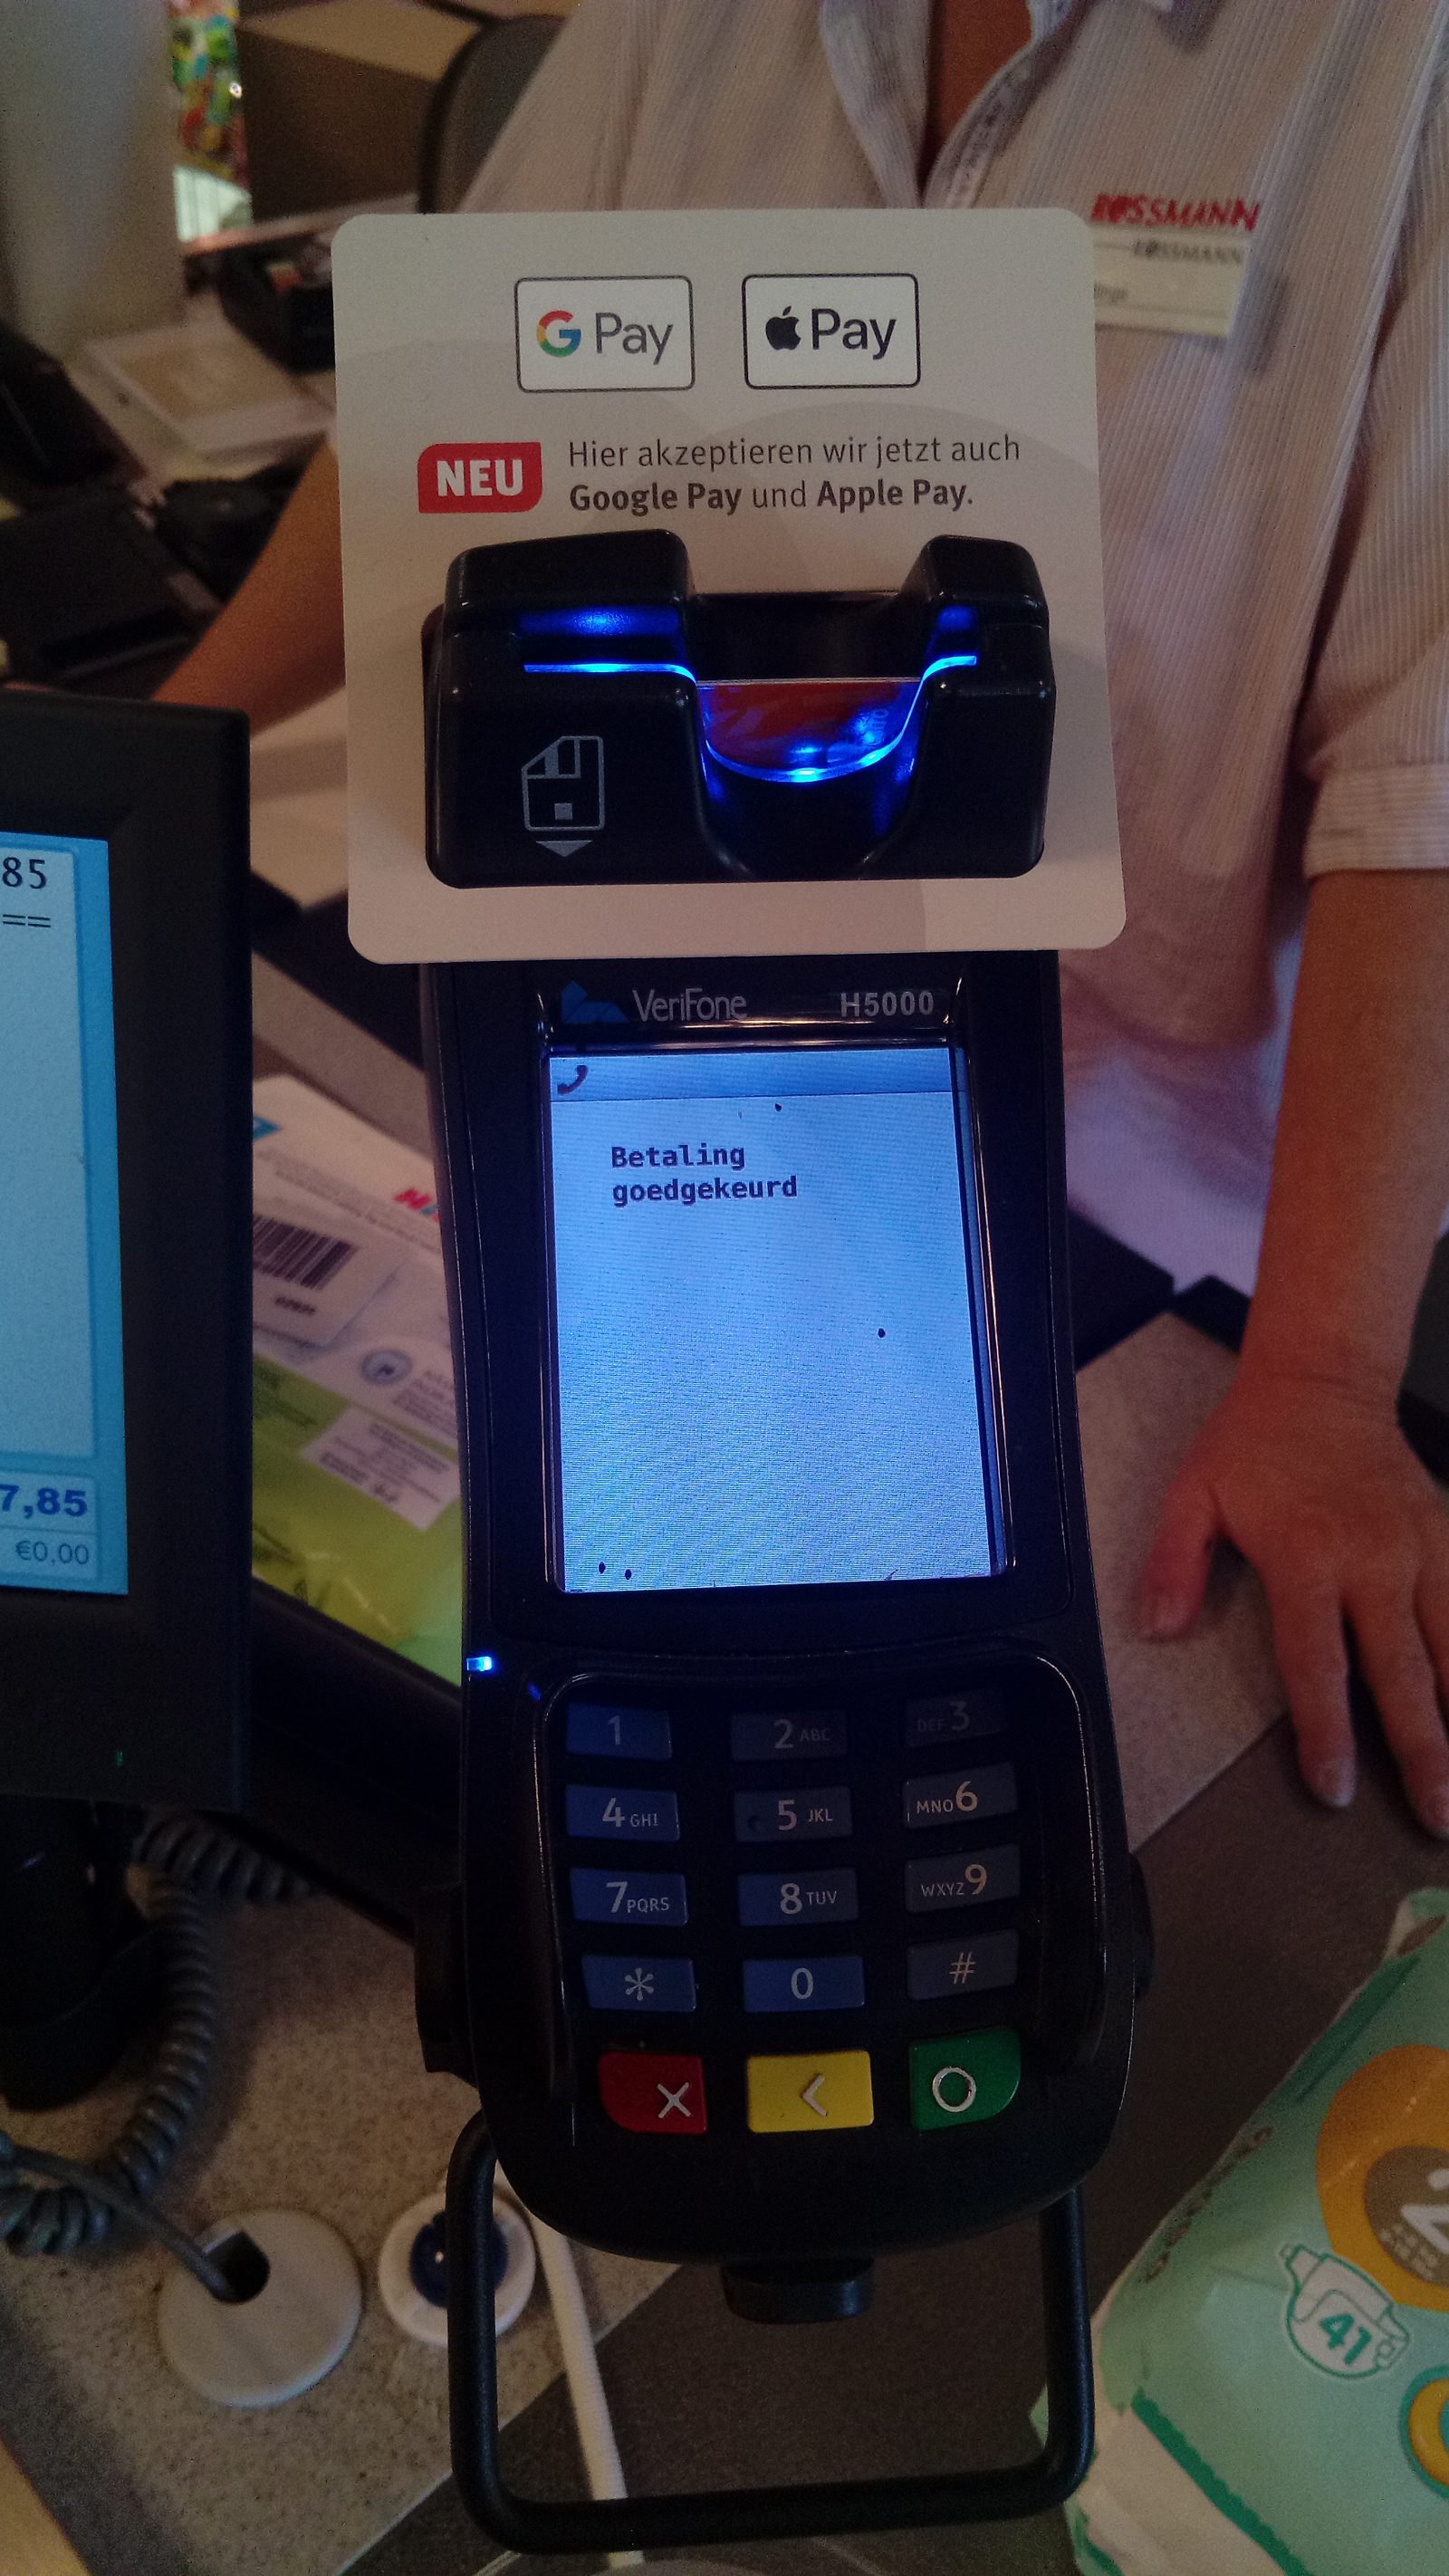
New Delhi: Apple Pay has officially launched in India, entering the country's crowded digital payments market nine years after the service debuted in the United States.
At launch the service supports only Axis Bank-issued Visa and Mastercard credit cards. Eligible users can add their cards to Apple Wallet on iPhones, iPads and Apple Watches and pay at thousands of stores, apps and websites; Mac support is expected to follow. Apple said users can authenticate with Face ID, Touch ID or a device passcode instead of entering a PIN or one-time password, and that real card numbers are never stored on its servers or shared with merchants — payments use a device-specific account number held in the phone's Secure Element.
Merchants on board include Blinkit, Croma, Ixigo, Reliance brands, Tata 1mg and Zomato, while payment companies Paytm, Razorpay, Pine Labs, PayU, Cashfree and JusPay have integrated Apple Pay for merchant acceptance.
The limited launch reflects what kept Apple out for nearly a decade. Apple's services chief Eddy Cue said in 2017 that the company was working to bring Apple Pay to India, but a 2018 Reserve Bank of India rule requiring payment data to be stored only within India stalled its plans. Apple's eventual fix was to keep tokenised payment data on users' phones and with card networks that already comply with the localisation rule, rather than copying it to Indian servers. Apple is also reported to be negotiating its cut of each card transaction, seeking roughly 15 to 20 basis points against the banks' offer of about 10.
Notably absent is UPI, which accounts for the bulk of India's digital payment volume. Adding it would require approval from the National Payments Corporation of India and a sponsor bank — neither is in place at launch. Talks with HDFC Bank and ICICI Bank are reportedly ongoing.
Sources
Share this story
Related articles
Rates can wait, the paperwork cannot: GST Council returns with compliance as the complaint
The 57th GST Council meets in New Delhi on October 8 after two postponements, with rates expected to stay put and process reforms - registration, returns, refunds and credit - on the table.
· 2 min read

Dearer loans from today: RBI lifts repo rate to 5.5% and signals prices will stay high
The RBI has raised the repo rate to 5.5% in its first hike in nearly four years and lifted its FY27 inflation view to 5.2%. Households will pay more on loans before they feel any relief on prices.
· 2 min read

Adani cuts a third of Mumbai's international flights, then gets summoned to Delhi
Adani-run Mumbai airport plans to withdraw 265 of 770 weekly international departure slots from October 25, citing Terminal 1 redevelopment. Airlines have rejected the cut, pointing to sold-out winter schedules — and the aviation ministry has been forced to intervene.
· 2 min read

Rupee sinks to 96.43 as RBI rushes in — and the worst may not be over
The rupee closed at 96.43 per dollar on Tuesday as the RBI likely sold dollars to slow the slide, traders said. With $77 billion in September hedges and $29 billion in FII outflows this year, the RBI's policy committee — meeting now — is expected to raise rates by 25 basis points on Wednesday.
· 2 min read